Author: Amanda Ahne
Asset Allocation Bi-Weekly – Breaking the Bond Fever! (September 21, 2026)
by Thomas Wash | PDF
After months of rising long-term yields, Treasury Secretary Scott Bessent has intervened in the bond market to help calm what he describes as a “fever.” The move reflects growing concern within the administration that fear has outweighed fundamentals in bond valuations, as investors grapple with rising energy costs tied to Middle East uncertainty and a growing US debt burden.
Earlier this month, the US Treasury Department announced plans to buy back up to $6 billion in long-dated securities, well above the $2 billion operation communicated to the market on August 19. The larger purchase underscores Secretary Bessent’s effort to dampen market volatility. Even so, Treasury’s more active role in the bond market has tested investors’ willingness to take Bessent’s guidance at face value. This uneasiness comes as the department seeks to manage the government’s expanding fiscal debt burden.
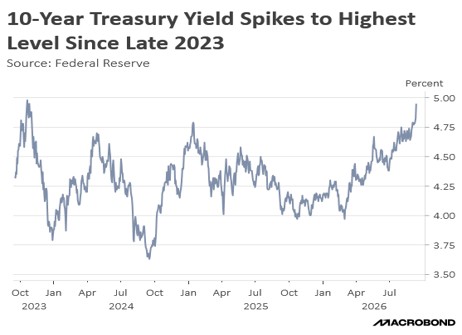
The announcement was poorly received by the market. Treasury securities sold off immediately, driving the 10-year yield to 4.85%, its highest level since November 2023. That rise was likely the opposite of what Bessent intended — the buyback had been meant to calm the bond market, not intensify the selloff. While some of this divergence was likely due to rising concern in the Middle East, it also seems to highlight the difficult task facing the Treasury as it continues to work towards steadying market conditions and exerting greater influence over borrowing costs.
The Treasury’s decision to expand its bond buybacks came amid ongoing debate over the market’s equilibrium price. Secretary Bessent noted that the intervention aimed to counteract market sentiment that would have prevented bond prices from reaching equilibrium. By removing discounted off-the-run bonds, the buybacks were intended to improve market liquidity and free up balance sheets, enabling banks and corporations to participate more actively in auctions.
Although Treasury buybacks have recently gained significant attention, the program has been in operation since 2024. When former Secretary Janet Yellen launched the initiative, it was designed to shift issuance toward shorter maturities, redirecting liquidity from the Federal Reserve’s overnight reverse repo facility into Treasury bills to ease funding stress and suppress term yields. This strategy served as a temporary bridge while awaiting central bank rate cuts, after which the Treasury could resume extending debt duration at lower interest rates.
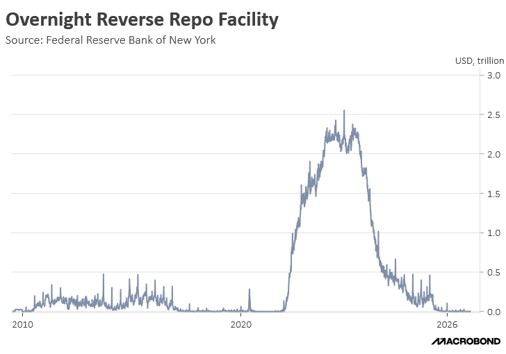
Secretary Bessent faces a similar market environment, albeit without the buffer of excess cash in the reverse repurchase facility. In its place, Bessent has been able to rely on the expansion of the Fed’s balance sheet through its reserve management purchases, which have allowed the Fed to buy Treasury bills. This policy action has accommodated the Treasury’s effort to rotate out of longer-dated bonds and into shorter-duration securities without adding to funding stress.
The effects on the market from the shift in Treasury issuance are most evident in auction results. The chart below shows the 12-month moving average of auction “tails” and “throughs.” An auction tails when the stop-out yield is higher than the prevailing when-issued yield, signaling softer-than-expected demand; it stops through when the stop-out yield is lower, indicating stronger demand.
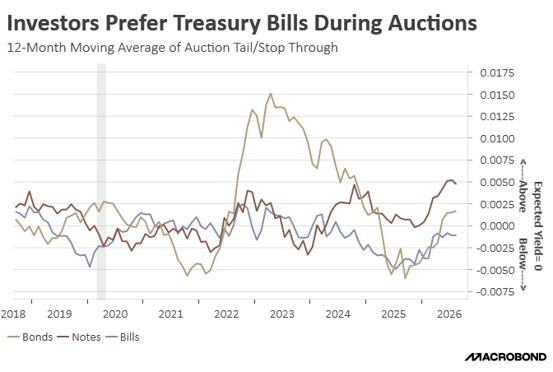
The Treasury’s decision under Secretary Yellen to tilt issuance toward shorter maturities occurred when auction results were showing signs of investor resistance, particularly at longer maturities. Although auction performance has generally been more stable under Secretary Bessent, the Treasury appears to be taking preemptive steps to prevent longer-dated supply from again encountering meaningful demand pressure.
Similar to former Secretary Yellen’s approach, Secretary Bessent’s expanded buyback strategy serves as a temporary bridge to mitigate upward pressure on yields. The Treasury is likely using these buybacks to facilitate a reallocation of its overall issuance composition, aiming to contain borrowing costs elevated by geopolitical tensions with Iran that have driven up inflation expectations and term premiums. Assuming the conflict eases — an outcome the White House suggests could materialize following the midterms — the Treasury is expected to scale back its active market interventions gradually.
If this thesis holds, while interest rates will probably remain elevated over the next few months, yields may not rise materially above current levels. Consequently, this environment could present an attractive entry point for investors seeking to extend duration. Over the long term, however, total returns for fixed income will remain tied to achieving price stability and seeing credible fiscal progress, whether through spending restraint or accelerated economic growth.
Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify
Daily Comment (September 18, 2026)
by Patrick Fearon-Hernandez, CFA, and Thomas Wash
[Posted: 9:30 AM ET] | PDF
Our Comment opens with our takeaways from the Bank of Japan’s latest rate decision. We then turn to trade, examining the recent easing of tensions between the US and China ahead of their talks. Next, we briefly cover the prospect of renewed US military operations in Iran, as well as a discussion about a hack into OpenAI. As always, we conclude with a review of recent domestic and international economic data.
Yen Weakens: The Bank of Japan (BoJ) is failing to reassure investors that it is prepared to tighten policy further in response to mounting inflation concerns. Overnight, the central bank raised interest rates to their highest level in more than 31 years, but offered mixed signals on the timing of any additional moves. The ambiguous guidance triggered a sell-off in the Japanese yen, as investors questioned the BoJ’s policy credibility. The market was focused on the meeting due to the possibility of closer policy coordination between Japanese and US authorities.
- The BoJ raised its benchmark interest rate by 25 basis points, from 1.00% to 1.25%. The hike was widely expected, as the central bank has been normalizing interest rates since 2024. While Governor Kazuo Ueda hinted at further hikes during the post-meeting press conference, citing a renewed focus on stabilizing inflation, the 7–2 vote (with the two dissenters favoring a hold) has raised doubts about whether the central bank will raise rates at its next meeting.
- The lack of conviction on future rate hikes is at odds with many of its peers. Based on the latest market-implied policy rates, the BoJ is the only G-7 central bank not expected to hike at its next meeting, with rate probability pricing in only a 31% chance, almost half that of its nearest peer, the European Central Bank, which sits at 60%. The potential widening of the interest rate differential has likely contributed to the depreciation of the yen.
- Prior to the meeting, the yen had strengthened on expectations that the BoJ would adopt a more assertive approach to policy tightening. Much of that shift followed comments from US Treasury Secretary Scott Bessent, who not only hinted that the BoJ should tighten more aggressively, but also appeared to suggest that he knew their decision prior to the vote. His remarks helped ease selling pressure on the yen and briefly fueled speculation that the BoJ could deliver a 50-basis-point rate increase at its latest meeting.
- A persistent decline in the Japanese yen could pave the way for more intervention by the US Treasury and the BoJ. It is commonly believed that the threshold for such action is when the yen weakens past 160 per dollar. If that happens, Japan’s Ministry of Finance could use its holdings of sovereign bonds to fund purchases of yen in the open market. The Treasury could also intervene, partly to stem Japanese sales of US Treasurys. Nevertheless, any move to strengthen the yen could weigh on sovereign bond prices.
The Calm Before Talks: Washington and Beijing are looking to ease tensions less than a week before the sides are set to meet for talks. On Thursday, as a sign of good faith, the US decided to delay its excess capacity tariffs until after the meeting. Meanwhile, China has offered an olive branch of its own, allowing the yuan to appreciate against the dollar. The moves come as the two sides prepare to hold talks on trade, geopolitics, and AI, in what could reshape the relationship between the world’s two largest economies.
- The decision to delay tariffs follows the US determination to replace the tariffs struck down by the Supreme Court. A July investigation into the use of forced labor in Chinese-made goods led to China receiving a 12.5% tariff, a rate China said was consistent with the truce the two sides struck earlier in the year. The new excess capacity tariff would add 7.5%, bringing the total to 20%, which will probably be discussed during the scheduled talks.
- Meanwhile, China’s decision to allow the yuan to appreciate against the dollar has also eased tensions. The yuan rose to its highest level against the dollar in nearly four years after the People’s Bank of China strengthened its currency fixing for an eighth day in a row. The move is likely to put White House officials at ease, following allegations that a weaker yuan has given Chinese goods a competitive advantage in trade.
- The decision by both sides to offer concessions ahead of the talks comes as the two countries prepare to address two major flashpoints: the war in Iran and AI competition. Both issues have grown in importance, as the US and China have taken opposing sides on the conflict and remain locked in intense competition over AI. The discussions should allow the two sides to find common ground and prevent an escalation of tensions, as both issues carry the risk of a direct conflict.
- As the talks approach, we expect to receive more details on discussions regarding the war in Iran and AI, as opposed to trade. If the two sides can reach a consensus that helps alleviate tensions in the Middle East, that could ease oil supply concerns, which in turn could be supportive of bond prices. Meanwhile, signs that the two countries won’t restrict mineral or technology exports to each other could be positive for AI-related stocks. However, any setback in the talks could weigh on market sentiment.
Escalation in Iran: President Trump has mentioned that he is considering resuming military operations in Iran as a way to end the conflict. While there has been some success in reopening the Strait of Hormuz, transportation is still well below prewar levels, and the conflict has since broadened into other areas, including the Red Sea. The decision comes as the cost to the US has made it difficult to maintain its blockade for much longer. The president is expected to meet with Israeli Prime Minister Benjamin Netanyahu next, in what could pave the way for his decision.
Hacking with AI: Independent researchers have already begun experimenting with ways AI can be used for cyberattacks. One test showed that they were able to use Claude AI to hack into an OpenAI chatbot of an employee, allowing it to read and suggest changes to its private cache. Once the test was complete, the researchers reported the vulnerabilities to OpenAI. The finding shows how people may attempt to exploit AI as it becomes more readily available, and it is likely to raise more questions about government oversight.
Daily Comment (September 17, 2026)
by Patrick Fearon-Hernandez, CFA, and Thomas Wash
[Posted: 9:30 AM ET] | PDF
Our Comment opens with our takeaways from today’s rate decision and what we could gather from the Fed’s communication. We then turn to the market’s reaction to the decision, examining its impact on equities and fixed income. Next, we briefly cover the EU’s push to have Canada become an associate member, as well as signs that AI companies are developing their own methods of self-regulating. As always, we conclude with a review of recent domestic and international economic data.
Fed Rate Decision: In an effort to curb inflation, the Federal Reserve unanimously voted to raise interest rates for the first time since 2023. The decision also signaled that the central bank is prepared to tighten monetary policy further. This increase in the federal funds rate comes amid an improving economy and rising energy prices, which have sparked concerns about inflation becoming unanchored. Furthermore, the move reinforces the central bank’s independence from political pressure.
- The rate decision cemented the Federal Reserve’s hawkish shift following weeks of speculation. The latest Summary of Economic Projections showed that Fed officials have revised their outlook for rates at the end of the year from remaining unchanged at 3.50%-3.75% to 4.00%-4.25%. The increase is driven by a rise in the central bank’s expectations for both growth and inflation, suggesting that it is no longer worried about the employment side of its mandate.
- During the press conference, Fed Chair Kevin Warsh emphasized that the rate decision was part of the central bank’s mission to return inflation to target. He noted that while Fed officials acknowledge they do not have control over some of the supply drivers of inflation, the rate increase was designed to prevent the second- and third-order effects those drivers could cause. He also suggested not only that Fed officials had judged conditions to be unrestrictive prior to the increase, but that current rates may still be accommodative.
- While Fed Chair Warsh was reluctant to offer much forward guidance, he did acknowledge one indicator that appears to be informing the decision-making process: the dispersion of inflation. According to Warsh, the share of components moving away from the 2% target was among the indicators that supported a rate hike at this meeting. Warsh previously noted that 54% of components were above 3%, down from a post-pandemic peak of 77%, but still well above the 22% seen prior to the pandemic.
- The Federal Reserve’s hawkish shift signals that its commitment to the 2% target remains intact. The Fed will likely receive some relief this month when the PCE updates its methodology, which is anticipated to show downward revisions to inflation. Thus, while the Fed appears hawkish and has signaled a willingness to hike rates further this year, there is still a chance that incoming data could lead it to hold steady.
The Market’s Take: The Fed’s decision to raise rates left more questions than it answered. While the market had largely priced in the possibility of a hike at the meeting, it seemed ill-prepared for the hawkish shift in the Summary of Economic Projections. Caught flat-footed, investors triggered a selloff across several securities and a rally in the dollar as lingering concerns about the direction of monetary policy persisted. The reaction serves as a reminder of how dependent the market has become on forward guidance, and how bumpy the adjustment may be without it.
- Despite the market being up prior to the Fed’s decision, several securities sold off during the session, a sign of position liquidations. The shift comes as investors look to reposition themselves following a change in Fed rate expectations. The Nasdaq 100 finished the day slightly higher, suggesting that investors remain confident in the technology sector, while gold was one of the worst performers, declining by about 1% following the announcement.
- One of the more noticeable market shifts following the announcement came in the yield curve, which underwent a bearish flattening as the short end rose faster than the long end. The 2-year Treasury yield rose roughly 10 bps, the 10-year finished the day up 6 bps, while the 30-year was roughly unchanged. The flattening reflects expectations that a hawkish Fed could weigh on growth without tipping the economy into recession.
- While the question going into the Fed announcement was whether it would tighten, the next few weeks will be about how much. The Fed has faced some pushback from the White House over its decision, but that has not yet impacted market rate expectations. The latest CME probabilities suggest the Fed could hike two to three more times this year, with only a 10% chance that it will leave rates unchanged. This sharp shift in outlook reflects a broad belief that the Fed will maintain independence in its rate decisions.
- The market reaction to the Fed was likely a knee-jerk response and may not reflect the view going forward. Sentiment should improve as the market obtains more information about the state of the economy, since higher interest rates and a moderation of concerns regarding oil supply should help alleviate inflation fears. While there may be some worry over White House meddling, we think the market will pay less attention to it now that the Fed has signaled it will hike, which should also provide some stability.
EU-Canada: The European Commission has pushed for Canada to become its first associate member. The move has already drawn the ire of President Trump, who recently indicated that the US and Canada were close to reaching an agreement. In response, he has described the EU’s outreach as a hostile act and has communicated a willingness to raise tariffs. The move is likely another example of the US’s desire to ensure a united North American trade policy as a precondition for maintaining ties with its North American allies.
AI Safety Risk: OpenAI unveiled a new framework on Wednesday for disclosing and tracking risks associated with rogue AI models. In the release, it reported previously undisclosed incidents in which AI behaved in ways counter to its intended use, including instances of concealing or fabricating information to return results. The move by the AI provider comes as tech companies look to demonstrate their ability to self-regulate in hopes of preventing the government from introducing new restrictions.
Daily Comment (September 16, 2026)
by Patrick Fearon-Hernandez, CFA, and Thomas Wash
[Posted: 9:30 AM ET] | PDF
Our Comment opens with our thoughts on the Fed ahead of today’s rate decision. We then turn to AI, examining the growing debate over regulation. Next, we cover legislation that would grant President Trump new trade authority, a meeting between US and Chinese officials ahead of their summit later this month, and the United Kingdom’s push to join a Canada-led defense bank. As always, we conclude with a review of recent domestic and international economic data.
Hawkish Sentiment: The Federal Reserve is set to deliver its rate decision later today, and the market is pricing in its first hike since 2023. Expectations of a rate hike have been increasing since the war in the Middle East started raising energy prices, leading to concerns about an uptick in inflation. While there have been worries that a hike could be the wrong move given that the source of inflation is being driven by supply factors as opposed to demand factors, questions about the Fed’s independence may mean that avoiding a rate hike could be costly.
- Sentiment has shifted regarding the Fed’s tilt over recent months after signs that the Fed was not moving closer to its 2% inflation target. Since the conflict began, the Fed has been progressively more hawkish. Although dot plots at the start of the conflict showed that FOMC members were confident in a rate cut this year, that confidence has given way to the central bank brushing aside any mention of a dovish tilt, and, at the previous meeting, a call for a rate hike from some officials.
- The shift in the FOMC has put pressure on Chair Warsh to offer some forward guidance, given that his stance has been somewhat unclear, but he has maintained the need for patience while also acknowledging the Fed’s commitment to price stability. During his comments at the Jackson Hole Symposium in August, he mentioned that the Fed “has work to do” to get inflation back to target, which has largely been seen as implicit support for a rate hike.
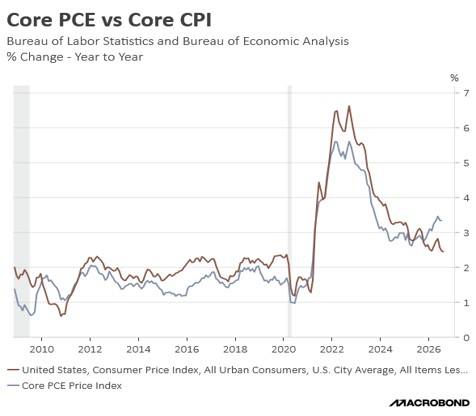
- The hawkish shift has occurred as key inflation measures have moved in opposite directions. Core CPI has edged closer to the Fed’s 2% target in recent months, while core PCE, the central bank’s preferred gauge, has moved further away from it. The divergence largely reflects differences in how the measures are weighted, particularly for housing — shelter has exerted more downward pressure on core CPI while having a much smaller effect on core PCE.
- The Fed is likely to raise rates, though we would not be surprised if it held policy steady or even opted for a larger-than-expected increase. A pause would probably reinforce the view that the committee is exercising patience in light of the conflict, while an outsized hike could help quell concerns about the Fed’s independence. As a result, today’s decision could materially reshape market expectations and set the tone for risk assets in the weeks ahead.
AI Safety Talks: There is growing discussion on Capitol Hill about how to best place guardrails for AI while also protecting against the negative consequences. On Tuesday, it was reported that a member of the Trump administration met with executives of Anthropic to discuss AI risks. This attempt to meet with business professionals comes as the White House has expressed wariness about adding restrictions that could slow the development of AI, which it views as a critical component of its national security strategy.
- White House efforts to understand the best way to guard against AI risks are fraught with growing disagreements. During a press conference in San Francisco, several tech executives argued that while the risks of AI are in fact real, the tech industry does not need new regulation. Meanwhile, at a separate conference in Washington, right- and left-wing populists Steve Bannon and Bernie Sanders agreed that there should be some oversight to prevent AI from hurting human interests.
- The discussions about what to do with AI are occurring at a time when the leading AI companies are purportedly preparing for IPOs. SpaceXAI, Anthropic, and OpenAI have all called for a global slowdown in development, despite having gone public or being prepared to do so. While these companies have continued to make promises of strong earnings power, their effort to moderate the pace of development has already been seen as a possible excuse if they fail to meet investor expectations.
- The market impact of these fears has been somewhat mild. Investors have been reducing their exposure to some chip stocks following worries that this could slow spending in the space, while software companies, which have been seen as possible casualties of the rise of AI tools, have benefited from the scare. The former may not last for long, as we think the push for the AI race is likely to benefit from government help; meanwhile, the latter’s gains may extend as AI fears continue to slow adoption rates.
- The concerns over potential guardrails have added to the fears about AI. However, its importance to US national security makes the government reluctant to offer any regulation that could prevent it from achieving its mission of eventually reaching artificial general intelligence (AGI), which would allow these models to reason and make logical decisions. This advancement would give the US a strong geopolitical advantage over its rivals.
Tariff Authority: On Tuesday, the House of Representatives advanced legislation that would give the president more authority to pursue tariffs. The proposal would allow the president to punish countries that purchase Russian energy. There is growing momentum to allow the White House more leeway in using trade and financial restrictions to prevent rivals and trade partners from going against US foreign policy and not following through on pledges.
Xi-Trump Summit: Roughly a week before President Trump is set to meet with his Chinese counterpart, both sides appear to be working to ease tensions. Treasury Secretary Scott Bessent is scheduled to meet Chinese Vice Premier He Lifeng on Sunday to discuss growing differences between the two countries, including AI development and trade. Although a major breakthrough is unlikely, the meeting could help set the tone for talks between the leaders of the world’s two largest economies.
UK Joining Canada: The United Kingdom is in discussions to join a Canada-led initiative for a defense bank. While the UK previously rejected the initial plan, it appears to have changed its tune, viewing the initiative as a potential aid in reaching its 3% of GDP defense spending target. The move is likely to further support aerospace and defense companies as Europe and other countries ramp up their military capabilities.
Daily Comment (September 15, 2026)
by Patrick Fearon-Hernandez, CFA, and Thomas Wash
[Posted: 9:30 AM ET] | PDF
Our Comment opens with our thoughts on how rising fears over AI are shaping the debate on global policy. We then turn to fixed income, examining the drivers behind the 10-year Treasury yield’s move to 5%. Next, we briefly cover China’s new travel restrictions and the Supreme Court’s ruling on mail ballots. As always, we conclude with a review of recent domestic and international economic data.
AI Fears? A push for a global slowdown in AI development has fueled a broader debate over ways to address geopolitical risks. On Monday, China rejected calls to restrict the use of its models in the US, arguing that it could disrupt the process of global governance of AI. Meanwhile, Canadian Prime Minister Mark Carney called for a global body to oversee AI development, arguing it would help ensure international standards. This debate over a global AI standard marks the first serious attempt at an international framework for the technology.
- Uneasiness over AI safety has led to a push for technological protectionism. Over the weekend, a top Chinese official in Beijing published an article warning that the technology could be abused by hostile forces to wage a propaganda and cognitive war against the government. He specifically referred to US models, including those from OpenAI and Anthropic. His comments followed concerns from Anthropic CEO Dario Amodei, who warned that China’s lead could pose a danger to the US and the world.
- However, there does seem to be a push for some form of international cooperation as a way to ensure AI is created safely. Carney has advocated for a board similar to the Financial Accounting Standards Board, which would create a unified set of governing rules to ensure AI is developed safely. The implication is that a rule-setting board would govern how public and private companies build and test AI models.
- The push toward either more protectionist AI policies or greater global cooperation reflects a world still adapting to the AI age. We think the global economic system may be shifting from one built primarily on trade to one increasingly built on technology. As a result, a dispute could emerge over how different AI models are permitted to operate across countries, particularly as the US and China continue to vie for supremacy in the space.
- The debate over the risks of AI could slow development, whether countries move toward protectionism or a global cooperative governing body emerges. While the latter is preferable, competition between the two largest economies makes the former more probable. This is apt to slow adoption, as it could prevent firms from accessing the lowest-cost alternatives. However, it may provide a boost to software-as-a-service companies, which are more likely to be threatened by the rapid adoption of AI tools.
Treasury Yield Peaks? The 10-year Treasury yield rose above 5% for the first time since 2023. The increase in yields comes as investors price in the possibility of a broadening conflict in the Middle East leading to further supply shocks in energy. This concern compounds the fact that inflation is likely to stay elevated, as government debt issuance and rising AI-related corporate debt continue to flood the market with supply. As a result, there are growing worries over what can be done to bring down global borrowing costs.
- The rise in bond yields comes in response to concerns about Iran and its proxies targeting energy infrastructure throughout the Middle East as it looks to gain leverage against the US. Over the last few days, Iran has used its proxies to broaden the war beyond the Strait of Hormuz. Most recently, the Iran-backed Houthis were able to take control of the Bab al-Mandab Strait and have tightened their grip on the coast of the Red Sea.
- The rise of the Houthi threat has put the US in a bind as it decides whether to expand its operations throughout the Middle East. Saudi Crown Prince Mohammed bin Salman has requested US military support as the kingdom looks to avoid having its oil exports blocked on two fronts. However, the US appears reluctant to provide that support, given its existing commitment to the Strait of Hormuz and unease about the further straining of its military resources.
- Oil markets have been hit hardest, as Saudi Arabia has struggled to export to the rest of the world. The kingdom is currently trying to resume operations at its East-West Pipeline, which has been a key means of selling oil while bypassing the Strait of Hormuz. There is hope that Saudi Arabia can rely on inventories held at one of its storage facilities on the Red Sea, as well as reserves stored in Egypt, but there are concerns that this would only serve as a short-term fix.
- While Treasury yields are elevated, it is important to remember that much of the risk is related to geopolitical tensions in the Middle East. Once there is a final resolution — preferably a reopening of the Strait of Hormuz, on which there has been considerable progress — long-duration bonds should be able to rally in response. In the meantime, however, rates could find considerable support due to oil supply uncertainty.
China Travel Restriction: Beijing has introduced a new travel restriction for civil servants and those working in sensitive industries. The move comes as the government aims to prevent the sharing of state secrets, particularly those related to its AI technology. The rule follows Meta’s blocked purchase of a Chinese AI company. The restriction comes as competition between the US and China over AI continues to heat up.
Mail Ballot Ruling: The Supreme Court rejected the White House’s request to restrict mail ballots for the midterm elections. The decision will allow states to continue sending out ballots in their usual manner. This ruling sets back the Trump administration’s efforts to restrict the use of mail-in voting as a way to ensure election integrity. While the issue is likely to be challenged further, its overall impact on November’s contest for either party is probably inconsequential regardless of the ruling.
Bi-Weekly Geopolitical Podcast – #92 “I Miss Recessions” (Posted 9/14/26)
Bi-Weekly Geopolitical Report – I Miss Recessions (September 14, 2026)
by Patrick Fearon-Hernandez, CFA | PDF
One of the most striking aspects of today’s world economy, and the United States economy in particular, is its ability to keep growing despite confidence-shaking events such as the US’s waning geopolitical power, large-scale wars, fracturing trade relations, global supply disruptions, an aging population, the coronavirus pandemic, persistent price inflation, dramatic policy change, and the rise of populist politics. In spite of all these challenges, gross domestic product (GDP) continues to expand, even after stripping out the impact of price changes.
GDP growth isn’t necessarily strong at the moment. In fact, in most key countries, it’s sitting below the long-run average rate. All the same, the continued expansion and lack of recessions would be expected to have big implications for consumers, businesses, and investors. Focusing on the US, this report examines why recessions have become so rare and what the implications might be for financial markets and investment strategy going forward.
Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify
Daily Comment (September 14, 2026)
by Patrick Fearon-Hernandez, CFA, and Thomas Wash
[Posted: 9:30 AM ET] | PDF
Our Comment today opens with an update on the war in Iran, where Iran-backed rebels in Iraq have apparently forced the shutdown of a key Saudi Arabian pipeline, boosting energy prices and driving down stock values around the world today. We next review several other international and US developments that could affect the financial markets today, including the weekend call from key US artificial intelligence leaders to “pace” the industry’s development and a review of upcoming monetary policy moves by key central banks this week.
United States-Israel-Iran: Saudi Arabia said over the weekend that it had shut down its critical East-West pipeline, which had allowed the kingdom to bypass the Strait of Hormuz and get some 7 million barrels per day of its crude oil to market through the Red Sea. The government said the pipeline had been targeted and damaged by drones apparently launched by Iran-backed militias in Iraq. The government also said it is repairing the pipeline; nevertheless, the incident highlights the vulnerabilities there.
- Now that the US and Israel have eroded more Iranian military power and the US has been able to escort more oil tankers through the strait, it appears that Iran is implementing a plan to lean more heavily on its proxy forces in the region to hurt the US and its allies.
- As investors begin to understand that shift and the now-demonstrated vulnerability of the East-West pipeline, global oil prices today have jumped about 3.4%, with near Brent crude oil futures trading at about $108.18. In turn, the jump in energy prices is weighing on stock values as well.
US Artificial Intelligence Industry: Anthropic chief executive Dario Amodei on Saturday published a 3,800-word essay calling for AI model development to proceed more slowly to avoid doomsday scenarios such as a rogue-agent takeover of the entire internet. Remarkably, a range of top AI executives including Elon Musk at SpaceXAI and Sam Altman at OpenAI publicly seconded the idea. As consensus on the issue apparently grows, it is becoming increasingly probable that Congress will finally be spurred to action to impose guardrails on the industry.
- Of course, the Chinese government and AI firms in China are so far showing no concern about the models’ rapid development. They are likely to keep charging ahead even if the US modelers slow down. Because of that, President Trump and officials associated with his administration are pushing back against a slowdown and calling for full steam ahead.
- In our view, there are now multiple headwinds growing for the AI industry in the US, including a competitive threat from the increasingly capable and low-cost Chinese models, public pushback against the data centers needed to run AI applications, and the new pressure to tighten regulations on the industry. If those headwinds continue to intensify, the risk of a pullback in AI-related equity valuations is expected to grow.
- In any case, the weekend discussion about deliberately slowing or “pacing” the momentum in AI development is weighing heavily on technology stock prices so far this morning.
China: The Beijing municipal government yesterday announced a ban not only on flying drones in the city but also on possessing, storing, transporting, or bringing them and their core components into the city, except in exceptional circumstances. The ban responds to a June incident in which a small plane flew into Beijing’s tallest building. The ban may also signal that as civilian drones become more commonplace around the world, they are likely to become regulated as the inevitable accidents happen, potentially crimping the budding industry.
India: The government has announced that it plans to source virtually all of its newly approved $11.6-billion military equipment spending from domestic sources, including an expanded role for the private sector. The move illustrates how governments around the world are prioritizing resilience, supply chain security, and domestic industrial development as they boost their defense budgets and respond to greater geopolitical tensions.
Sweden: The country’s parliamentary election yesterday has become the closest ever, with fewer than 30,000 votes currently separating the left-wing opposition bloc from the right-wing government as hundreds of thousands of overseas votes and late ballots are still to be counted. Electoral authorities don’t expect to announce the final results until Wednesday or Thursday.
US Monetary Policy: The Fed begins its latest policy meeting tomorrow, with its decision due out on Wednesday at 2:00 PM ET. Based on the latest interest-rate futures trading, investors widely expect the policymakers to hike their benchmark fed funds rate by 25 basis points to a range of 3.75% to 4.00%. That expectation stems from both the continued high readings for consumer price inflation and recent hawkish statements by Chair Warsh and other policymakers.
- Still, because of the risk of political blowback from the White House or other concerns, there is probably still some chance that the policymakers could simply hold rates steady.
- Such a decision would likely spark significant volatility across a range of asset markets.
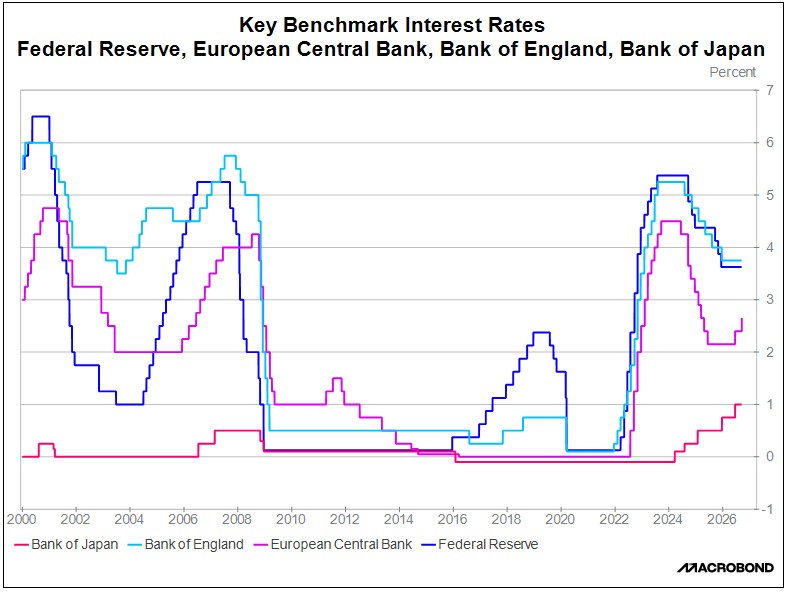
UK Monetary Policy: In contrast with the Fed, the Bank of England is expected to hold its benchmark interest rate steady at its policy meeting later this week. However, analysis by the Financial Times suggests that relatively brisk economic growth coupled with rising energy costs due to the war in Iran could force the central bank to boost rates later this year. Any such rate hike would be the BOE’s first in more than four years.
Japan Monetary Policy: Economist surveys also show that the Bank of Japan is widely expected to hike its benchmark interest rate again when it holds its latest policy meeting this week. Importantly, the normalization of Japanese interest rates after decades of extraordinarily low rates continues to contribute to an unwinding of the yen “carry trade.” In turn, that is causing significant volatility in the global currency markets and broader financial markets.